Aberdeen Investments: Chinese innovation is underappreciated by the market
Markets have overly punished China equities with long-term innovation drivers, according to Aberdeen Investment’s Nicholas Yeo.

Markets have overly punished China equities with long-term innovation drivers, according to Aberdeen Investment’s Nicholas Yeo.
Markets have overly punished China equities with long-term innovation drivers, according to Aberdeen Investment’s Nicholas Yeo.

RQI applies a research-driven, quantitative investment process to analyse a broad universe of companies.
JP Morgan Asset Management in its long-term projections says it expects alternatives to enhance returns in a balanced portfolio of stocks and bonds.
JP Morgan Asset Management in its long-term projections says it expects alternatives to enhance returns in a balanced portfolio of stocks and bonds.
Diversification requires looking beyond asset class labels to understand underlying risks, according to BlackRock.
Sponsored by Loomis Sayles & Natixis
The Growth Equity Strategies Team at Loomis Sayles, an affiliate of Natixis Investment Managers, demonstrates that patience, discipline and conviction result in consistent, peer-leading risk-adjusted compounding over cycles.
RQI applies a research-driven, quantitative investment process to analyse a broad universe of companies.
This week, FSA compares the Robeco Smart Energy fund and the Pictet Clean Energy Transition fund.
Markets have overly punished China equities with long-term innovation drivers, according to Aberdeen Investment’s Nicholas Yeo.
Markets have overly punished China equities with long-term innovation drivers, according to Aberdeen Investment’s Nicholas Yeo.
JP Morgan Asset Management in its long-term projections says it expects alternatives to enhance returns in a balanced portfolio of stocks and bonds.
This week, FSA compares the Robeco Smart Energy fund and the Pictet Clean Energy Transition fund.
This week, FSA compares the Robeco Smart Energy fund and the Pictet Clean Energy Transition fund.
BlackRock, Vanguard, and Fidelity form top three managers.
Markets have overly punished China equities with long-term innovation drivers, according to Aberdeen Investment’s Nicholas Yeo.
Markets have overly punished China equities with long-term innovation drivers, according to Aberdeen Investment’s Nicholas Yeo.
The Hong Kong finance veteran has moved to M&G.
Markets have overly punished China equities with long-term innovation drivers, according to Aberdeen Investment’s Nicholas Yeo.

China’s stock market has slumped during the past year, with losses accelerating over the past few months as investors dump artificial-intelligence (AI) stocks on valuation fears.
The market has also been held back by stubbornly persistent domestic consumption weakness and a lack of bolder stimulus measures by Beijing.
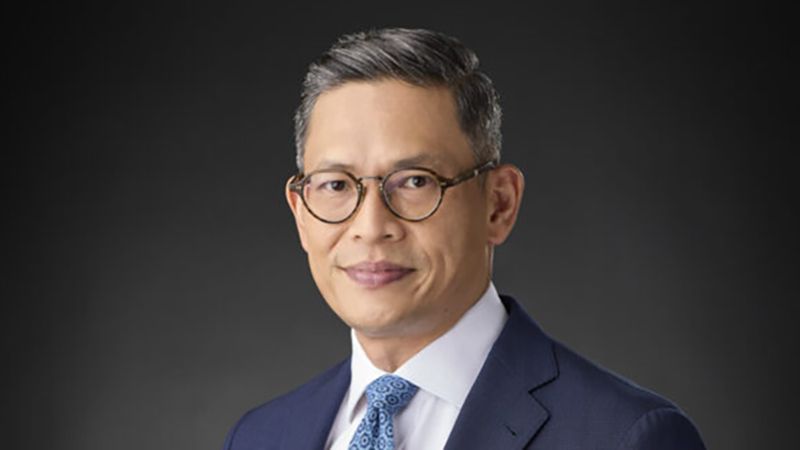
However, investors would benefit from separating the wheat from the chaff in sectors where China has an edge, according to Aberdeen Investment’s head of China equities Nicholas Yeo (main picture).
He told FSA in an interview that the recent downturn has created opportunities in AI infrastructure, pharmaceuticals and robotics, all areas where the world’s second largest economy has a lead in innovation and government mandated support.
“The market has overly penalised the innovation side of China,” he said. “Looking at stocks from the bottom-up and doing the research on the ground, we cannot be more impressed by some of the innovation that is taking place.”
Although the market has been disappointed recently by the lack of support for equities by China’s authorities, Yeo said recent weaker export data could indicate support might be coming.
“The economy is slowing down quite a lot, and with oil prices being so high, I don’t think the government can continue to rely on exports as the main engine of growth,” he said.
“High prices means that external demand may also weaken, then maybe that is a better time to pull the lever on domestic stimulus.”
However, even if no stimulus measures come to fruition, Yeo points out that there are some industries in China with an edge.
“An area that we focus on where China has an edge is in PCBs (the printed circuit board), where it may sound commoditized, boring, but because of AI, they have climbed up the value chain.”
“The demand of AI means that PCB production has to be a lot more efficient, a lot more sophisticated, so the barrier to entry has increased in what used to be a low barrier industry.”
“China has a dominant global market share in solar panels, batteries and transformers,” Yeo added.
And given the recent concerns about the lack of power infrastructure in the US being an impendent to their AI ambitions, he argued that China’s dominance in the transformers industry is notable.
Yeo also asserted that China has a unique edge in drug innovation, pharmaceuticals and healthcare: “For many of the drugs that have gone into human trial in the latter phases of drug development, about 50% are coming out of China,” he said.
“Innovation has become a national security concern, and in certain areas, China is already ahead of the rest of the world,” he added.
Aside from some specific industries, Yeo points out that there is also a dividend-up story in China that is perhaps overlooked.
“The dividend-up story in China is quite meaningful,” he said. “We’re looking at something close to a 3% dividend as a market. That is being demanded by the regulators and government.”
“The authorities are aware that it cannot be dominant if their equity market is not sufficient to fund Chinese innovation in the same way that the US equity market does.”
“The government not allowing companies to raise capital so easily, increasing shareholder returns – all of that is to help its capital markets so it can do its job to help fund innovation.”
This week, FSA compares the Robeco Smart Energy fund and the Pictet Clean Energy Transition fund.
The Hong Kong finance veteran has moved to M&G.
JP Morgan Asset Management in its long-term projections says it expects alternatives to enhance returns in a balanced portfolio of stocks and bonds.